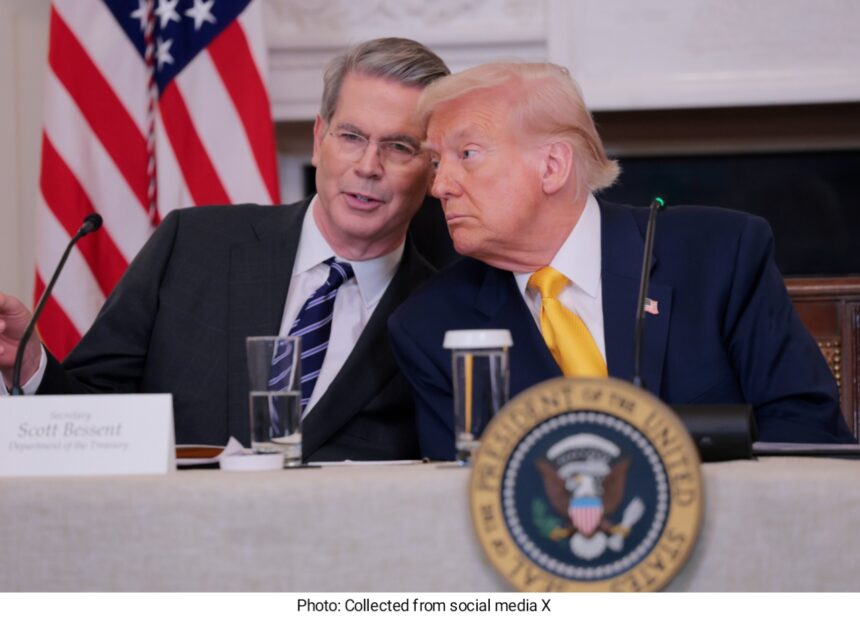
The Trump administration is moving to make immigration eligibility part of the process for taxpayers seeking the refundable portions of several major federal tax credits, a proposed change that could affect millions of people who file US tax returns. The US Treasury Department and Internal Revenue Service announced proposed regulations in August 2026 that would restrict the refunded portion of four refundable tax credits to taxpayers who meet specific citizenship or immigration-status requirements under federal law. The affected credits are the Earned Income Tax Credit, Child Tax Credit, American Opportunity Tax Credit and Adoption Tax Credit. Under the proposal, taxpayers seeking the refundable portion of these credits would have to certify under penalty of perjury that they are US citizens, US nationals or “qualified aliens” eligible to receive the federal benefit. The proposed policy is based on the Personal Responsibility and Work Opportunity Reconciliation Act of 1996, commonly known as PRWORA. Treasury and the IRS argue that the refunded portion of certain refundable tax credits should be treated as a federal public benefit under that law. PRWORA generally restricts access to federal public benefits for people who do not fall within the law’s definition of a qualified alien, subject to limited exceptions. The administration says the proposed regulations are intended to prevent federal benefits from being paid to people who are legally barred from receiving them. Under the proposed system, taxpayers would not necessarily have to provide immigration documents with their tax return. Instead, those seeking a qualifying refundable credit that produces a federal public benefit would make a declaration on the tax return or an attached schedule stating that they meet the eligibility requirements. The declaration would be made under penalty of perjury, meaning the taxpayer would be legally responsible for the accuracy of the information provided. The IRS says the requirement would apply when a taxpayer claims the refunded portion of one or more of the four affected credits. The proposed rule makes an important distinction between a tax credit and its refundable portion. A taxpayer may qualify for a credit under the tax code and use it to reduce federal income tax liability. But when the amount of an affected refundable credit exceeds the taxpayer’s federal income tax liability, the excess can become a refund. Under the proposed regulations, that refunded portion would be treated as a federal public benefit subject to the immigration eligibility restrictions. A taxpayer who is not eligible for the federal public benefit could still receive the portion of the credit that is otherwise allowed to offset tax liability. The draft 2026 Schedule 3-A provides a clear indication of how the new certification could appear on federal tax forms. The draft schedule is titled “Federal Public Benefit” and is intended for taxpayers claiming the Earned Income Credit, Additional Child Tax Credit, refundable American Opportunity Credit or refundable Adoption Credit. One of the proposed questions asks whether the taxpayer or the taxpayer’s spouse is a US citizen, US national or qualified alien. The draft form then directs taxpayers based on their answer. The IRS has listed the 2026 Schedule 3-A among its draft tax forms. Because the document is still marked as a draft, its contents may change before the final tax forms and instructions are issued. The existence of the draft form therefore does not mean that the proposed certification requirement has already become a permanent part of federal tax law. The administration’s proposal could have a broad reach because millions of US taxpayers claim the affected credits each year. Treasury and the IRS estimate that about 49 million federal individual income tax returns for tax year 2026 will claim at least one of the four affected refundable credits. Of those, the agencies estimate that about 24 million taxpayers will claim an affected refundable credit that produces a federal public benefit under the proposed framework. The government does not have direct data showing the immigration status of every taxpayer who receives these credits, so Treasury and the IRS say they cannot precisely determine how many people would be denied the refunded portion under the proposal. Their regulatory analysis estimates that between 200,000 and 700,000 taxpayers could potentially be ineligible because they do not meet the qualified-alien requirements under PRWORA. The agencies stress that this is an estimate based on available data and assumptions rather than a direct count of affected taxpayers. The estimated financial impact could also be significant. Treasury and the IRS estimate that the average federal public benefit associated with the refunded portion of the affected credits would be about $3,656 in 2026. Applying that figure to the estimated number of potentially ineligible taxpayers produces an estimated range of roughly $700 million to $2.6 billion in credits that could be disallowed under the proposed rules. These figures are estimates, and the agencies note that they do not account for all possible changes in taxpayer behavior. The Earned Income Tax Credit is among the most significant programs affected by the proposal. The credit is designed to provide tax relief to eligible low- and moderate-income workers, while the Child Tax Credit provides tax benefits to qualifying families with children. The American Opportunity Tax Credit is connected to eligible higher-education expenses, and the Adoption Tax Credit provides tax relief for qualifying adoption costs. Under the proposed regulations, the restriction would apply only to the refunded portion that is treated as a federal public benefit, rather than eliminating the underlying tax credits altogether. The proposed rules also address married couples who file joint tax returns. According to the Treasury and IRS proposal, if a married couple files jointly and otherwise qualifies for an affected refundable tax credit, only one spouse needs to be a US citizen, US national or qualified alien for the joint return to receive the refunded portion. This provision is intended to establish how the immigration eligibility requirement would operate in joint filing situations. The administration’s move has broader implications because it would bring an immigration-status certification into the federal income-tax filing process. Tax returns traditionally collect extensive financial and personal information, but the proposed Schedule 3-A would add a direct eligibility declaration concerning citizenship or qualified immigration status for taxpayers seeking the relevant federal public benefit. The change could therefore make the annual tax filing process an additional point at which immigration eligibility is formally declared to the federal government. The Treasury Department argues that this is necessary to enforce existing federal restrictions on public benefits. Treasury Secretary Scott Bessent said the administration’s position is that taxpayers should not finance benefits for people who are legally barred from receiving them. The IRS similarly says the proposed regulations are intended to clarify and enforce existing law rather than create a new category of federal public benefit. The proposal is also drawing attention because of the potential consequences for people who have lawful but complex immigration circumstances. Under the federal rules referenced by Treasury, “qualified aliens” can include lawful permanent residents, refugees, people granted asylum and certain other categories defined by federal law. The proposed regulations therefore do not simply divide taxpayers into citizens and undocumented immigrants. They establish a broader legal category of people who may qualify for the federal public benefit even though they are not US citizens. Another important issue is how information supplied through the tax system could be handled. The proposed regulations themselves focus on eligibility for the refunded portion of the affected credits and require a declaration of eligibility. They do not, by themselves, establish a general immigration-enforcement system through the IRS. Nevertheless, because taxpayers would be required to make a legal declaration about their status, the proposal has raised wider questions about how immigration-related information collected during tax administration could interact with other federal systems and enforcement priorities. Those questions go beyond the specific eligibility rule contained in the proposed regulations. The proposed regulation is currently part of a formal federal rulemaking process. The IRS published the proposal in the Internal Revenue Bulletin and opened a period for public comments. According to the IRS, written comments are due by October 5, 2026, while a public hearing is scheduled for October 14, 2026, unless it is cancelled because no requests to speak are received by the deadline. The rules would generally apply to tax years ending on or after the date the regulations are published as final regulations. This means taxpayers should not treat the proposal as a completed rule at this stage. The final regulations could retain, modify or potentially change parts of the proposal after the government reviews public comments and completes the rulemaking process. The draft Schedule 3-A nevertheless offers an important preview of what the change could look like for taxpayers. The draft asks whether the taxpayer or spouse is a US citizen, US national or qualified alien and provides instructions for determining how the refundable portion of the affected credits would be handled. The IRS has explicitly labeled the form as a draft, meaning taxpayers should wait for the final version and official instructions before relying on its current wording. The proposed change reflects the Trump administration’s broader effort to enforce immigration-related eligibility restrictions across federal programs. At the same time, its application through the tax system represents a significant procedural change for people who rely on refundable credits. The final outcome will depend on the rulemaking process, public comments and any revisions made by Treasury and the IRS before the regulations are finalized. For now, the central fact is that the federal government has proposed requiring taxpayers who seek the refunded portion of four specific refundable tax credits to certify that they meet federal citizenship or qualified-immigration-status requirements. The requirement has not yet become a final regulation, and the 2026 Schedule 3-A currently available from the IRS remains a draft document.
Trump administration’s new proposal: Federal tax filings may require citizenship or immigration-eligibility information